Reframing The Cost of Rebalancing – An Opportunity Cost Analysis
 Naaz Scheik· July 29, 2026
A Technology Founder’s Take on Rebalancing
I’ve noticed something over the years.
When firms talk about rebalancing, it’s always seen as a functional part of advisory operations.
Most if not all RIAs think of the “cost of rebalancing” as a payroll cost, which is #of hours advisors spend doing rebalancing-related tasks * the average per-hour cost of an advisor.
But I’ve come to believe that this perception of cost is a direct consequence of rebalancing being seen as a time-constrained activity, not a cost center – and I want to challenge that notion.
The question I want to deal with isn’t “how long rebalancing takes?”
It’s what your current process is costing your business.
Those are two very different conversations.
One measures activity.
The other measures the quality of the system that produces that activity.
Today, I want to analyze the cost of rebalancing from a lens of opportunity cost.
#of hours advisors spend doing rebalancing-related tasks * the average per-hour cost of an advisor
vs.
#of hours advisors spend doing rebalancing-related tasks * avg billable rate per-hour of an advisor
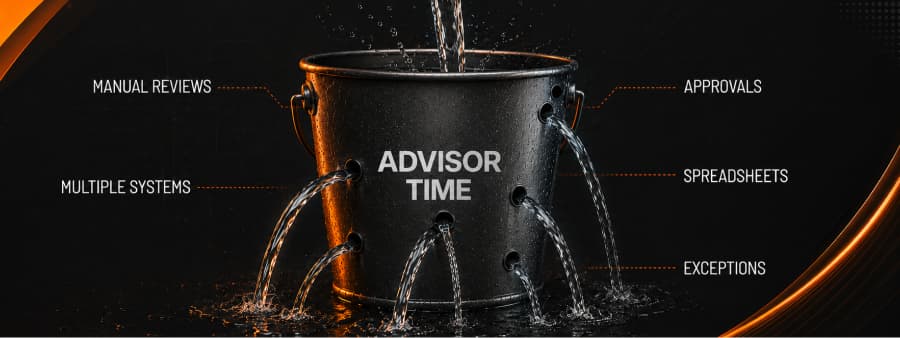
This is the difference between firms that scale processes systemically from those that apply a paper tape on a cracked flood gate.
The Pattern I Keep Seeing
The truth is – rebalancing costs money, and it can be tedious.
Checking errors manually, drift analysis and optimization, tax optimizations, organizing sheets, consolidating different custodian rebalancers to create internal reports and analysis, error handling, consolidating held-away assets, and even household optimizations are often dealt with manually – with custodial rebalancers only lifting the partial weight of the process for RIAs.
You spend a lot of time per year, per advisor, performing a function and its subsidiaries that simply doesn’t generate direct revenue.
But with most firms, this is never flagged as an operational failure – it’s seen as an inevitability of the process. Thus, every quarter you have RIAs facing bottlenecks, time-sensitivity, and work pressure. This is a common storyline for all RIAs – thus a pattern.
The most common solution implemented?
Hiring more people. And though that seems to help in the short run with pressure release, it adds strain on the business in the long-run.
So, let’s analyze this misdiagnosis.
The Misdiagnosis Analysis – A Business Issue
For more than three decades, I’ve worked with wealth management firms of different sizes and operating models.
Some manage hundreds of millions in assets, while others oversee tens of billions.
Their client bases are different, their investment philosophies vary, and their internal structures have evolved in unique ways. Yet despite those differences, I continue to encounter the same operational pattern.
When operational burden begins to feel heavier, and errors and delays seep into the everyday work, leaders often assume they have a capacity problem.
They hire another operations analyst, create another review step, or ask advisors to spend more time validating portfolios before trades are executed.
Sometimes they invest in another technology platform without redesigning the workflow that surrounds it. These decisions create temporary relief because additional people and tools absorb today’s workload.
What they rarely do is remove the underlying complexity. The work still exists; it is simply distributed across more individuals. Over time, communication expands, approvals multiply, and coordination becomes an increasingly significant part of the job.
From the outside, the firm appears to be growing successfully. Inside the organization, however, operational complexity continues to accumulate until it becomes difficult to distinguish productive work from the effort required simply to keep the business moving.
Rebalancing Isn’t the Work. It’s a Signal.
I don’t think of rebalancing as a trading task anymore. I think of it as an operational signal. It tells me how efficiently an organization converts investment decisions into client outcomes.
When a firm can move from investment intent to portfolio execution through a disciplined, repeatable process, it usually reflects a broader level of operational maturity.
The opposite is equally revealing.
If a rebalance requires multiple spreadsheets, several manual reviews, disconnected applications, and constant exception handling, the issue extends well beyond the trading process itself.
Those symptoms point to an operating model that has gradually become dependent on human coordination rather than systematic execution.
This is where the alternative philosophy becomes relevant. Manual work is rarely expensive because of the minutes involved.
It becomes expensive because of the opportunities it consumes.
Every hour an experienced advisor spends validating trades is an hour that could have been spent strengthening client relationships.
Every operations specialist resolving avoidable exceptions is capacity that cannot be applied to higher-value work.
Most firms can measure the hours involved in rebalancing.
Far fewer understand the cumulative organizational cost created by the way those hours are spent.
Even at an average billing rate of $200, an advisor spending 20 hours in manual rebalancing processes is an opportunity cost of $4,000 per cycle.
Organizations that can implement workflow, technology, or infrastructural changes to automate this process by even 50% would be able to allocate an additional $2,000 per cycle in billable hours.
Multiply that by the number of advisors, and you’ll see the business logic for investing in improving and automating this workflow through structured technological implementation.
With 5 full time RIAs, and a quarterly rebalancing cycle, that’s $40,000 in opportunity cost per year.
This is why the efficiency of the rebalancing process is a key indicator of a firm’s operational maturity and business health.
The Firms That Think Differently
The firms that impress me aren’t necessarily the ones with the most sophisticated investment models or the largest technology budgets.
They’re the ones that approach rebalancing as an operational decision rather than simply an investment function.
They recognize that every workflow reflects a design choice, and those choices determine whether growth becomes easier or more difficult over time.
As a result, they ask different questions. Instead of asking how quickly trades can be processed, they examine how many manual touchpoints exist before execution.
They look at how many exceptions genuinely require human judgment and how many exist because systems fail to communicate effectively.
They evaluate how many platforms must exchange information before a portfolio reaches its target allocation and whether experienced professionals are spending their time where they create the greatest value.
And this is the lynchpin of this philosophy. Firms that allow advisors to maximize hours spent in work that generates the greatest value are the one that scales robustly, and expand their business margins.
These are not technology questions. They are leadership questions.
The objective isn’t simply to automate trades.
It is to reduce unnecessary friction across the operating model so that skilled people spend more time making meaningful decisions and less time managing repetitive processes.
When firms make that shift, efficiency becomes a natural outcome of better design rather than harder work.
Cost Is Bigger Than Payroll
This is the structural cost, the hidden cost created by the way an organization functions every day. These costs don’t appear as individual line items on a financial statement, yet they influence almost every aspect of performance.
Structural cost includes delayed execution, fragmented workflows, inconsistent client experiences, duplicated effort, and talented employees spending their time coordinating repetitive activities instead of exercising professional judgment.
Individually, these inefficiencies often seem insignificant.
Collectively, they become one of the largest barriers to sustainable growth because they quietly consume organizational capacity.
I’ve seen firms invest heavily in expanding teams while leaving the underlying operating model unchanged. Initially, those investments appear successful because additional people reduce immediate pressure.
Over time, however, the same inefficiencies resurface in a larger organization with more communication layers and greater coordination requirements.
The business becomes bigger, but it doesn’t necessarily become stronger.
What I Would Measure Instead
If I were evaluating an advisory firm’s operating model today, I wouldn’t begin by asking how long rebalancing takes. That answer tells me very little about whether the organization is becoming more efficient as it grows.
Instead, I would focus on the questions that reveal how work actually flows through the business.
How many people are involved in a typical rebalance?
How many decisions require manual intervention?
How many exceptions exist because systems aren’t aligned?
How many advisor hours disappear into operational work each month?
Most importantly, how much capacity could be recovered if repetitive work were removed entirely?
These questions expose the structural characteristics of the organization rather than simply measuring its activity.
The answers provide a much clearer picture of operational health. Efficiency is not about completing the same work faster. It is about designing the business so that unnecessary work gradually disappears.
When leaders begin measuring the cost of friction instead of the duration of tasks, they often discover opportunities that were invisible when they were focused only on time.
A Better Question
Every founder eventually reaches a point where adding more people stops producing proportional results. That moment usually marks the transition from managing growth to designing an organization capable of sustaining it.
In my view, rebalancing belongs in that conversation because it exposes how effectively an advisory firm converts expertise into consistent execution.
I don’t see rebalancing as a technology problem, nor do I see it solely as a portfolio management function. I see it as one of the clearest indicators of operational maturity. A well-designed rebalancing process reflects disciplined workflows, aligned systems, and thoughtful leadership decisions.
A fragmented process often reveals deeper structural issues that extend well beyond trading itself.
So the next time someone tells you their rebalancing process takes two days, resist the temptation to ask whether it can be completed in one. Ask a more valuable question instead.
What is your current process actually costing your business?
In my experience, that’s the question that changes how leaders think about growth, and ultimately how they build firms that continue to scale without becoming heavier.